NCUA published a formal AI Compliance Plan and AI Resource Hub (ncua.gov/ai, September 2025). The agency appointed a Chief AI Officer (Amber Gravius) to oversee AI governance for the 2025-2026 examination cycle. NCUA's guidance aligns with the NIST AI Risk Management Framework, which means credit unions must document artificial intelligence model inputs, outputs, and governance decisions in their lending operations.
Any AI system influencing a lending decision must produce an auditable rationale. When a decision model recommends approval, denial, or pricing, the institution must be able to show an examiner exactly what inputs drove that output and who approved the decision logic. Credit unions without explainable, audit-ready AI face growing examination risk.
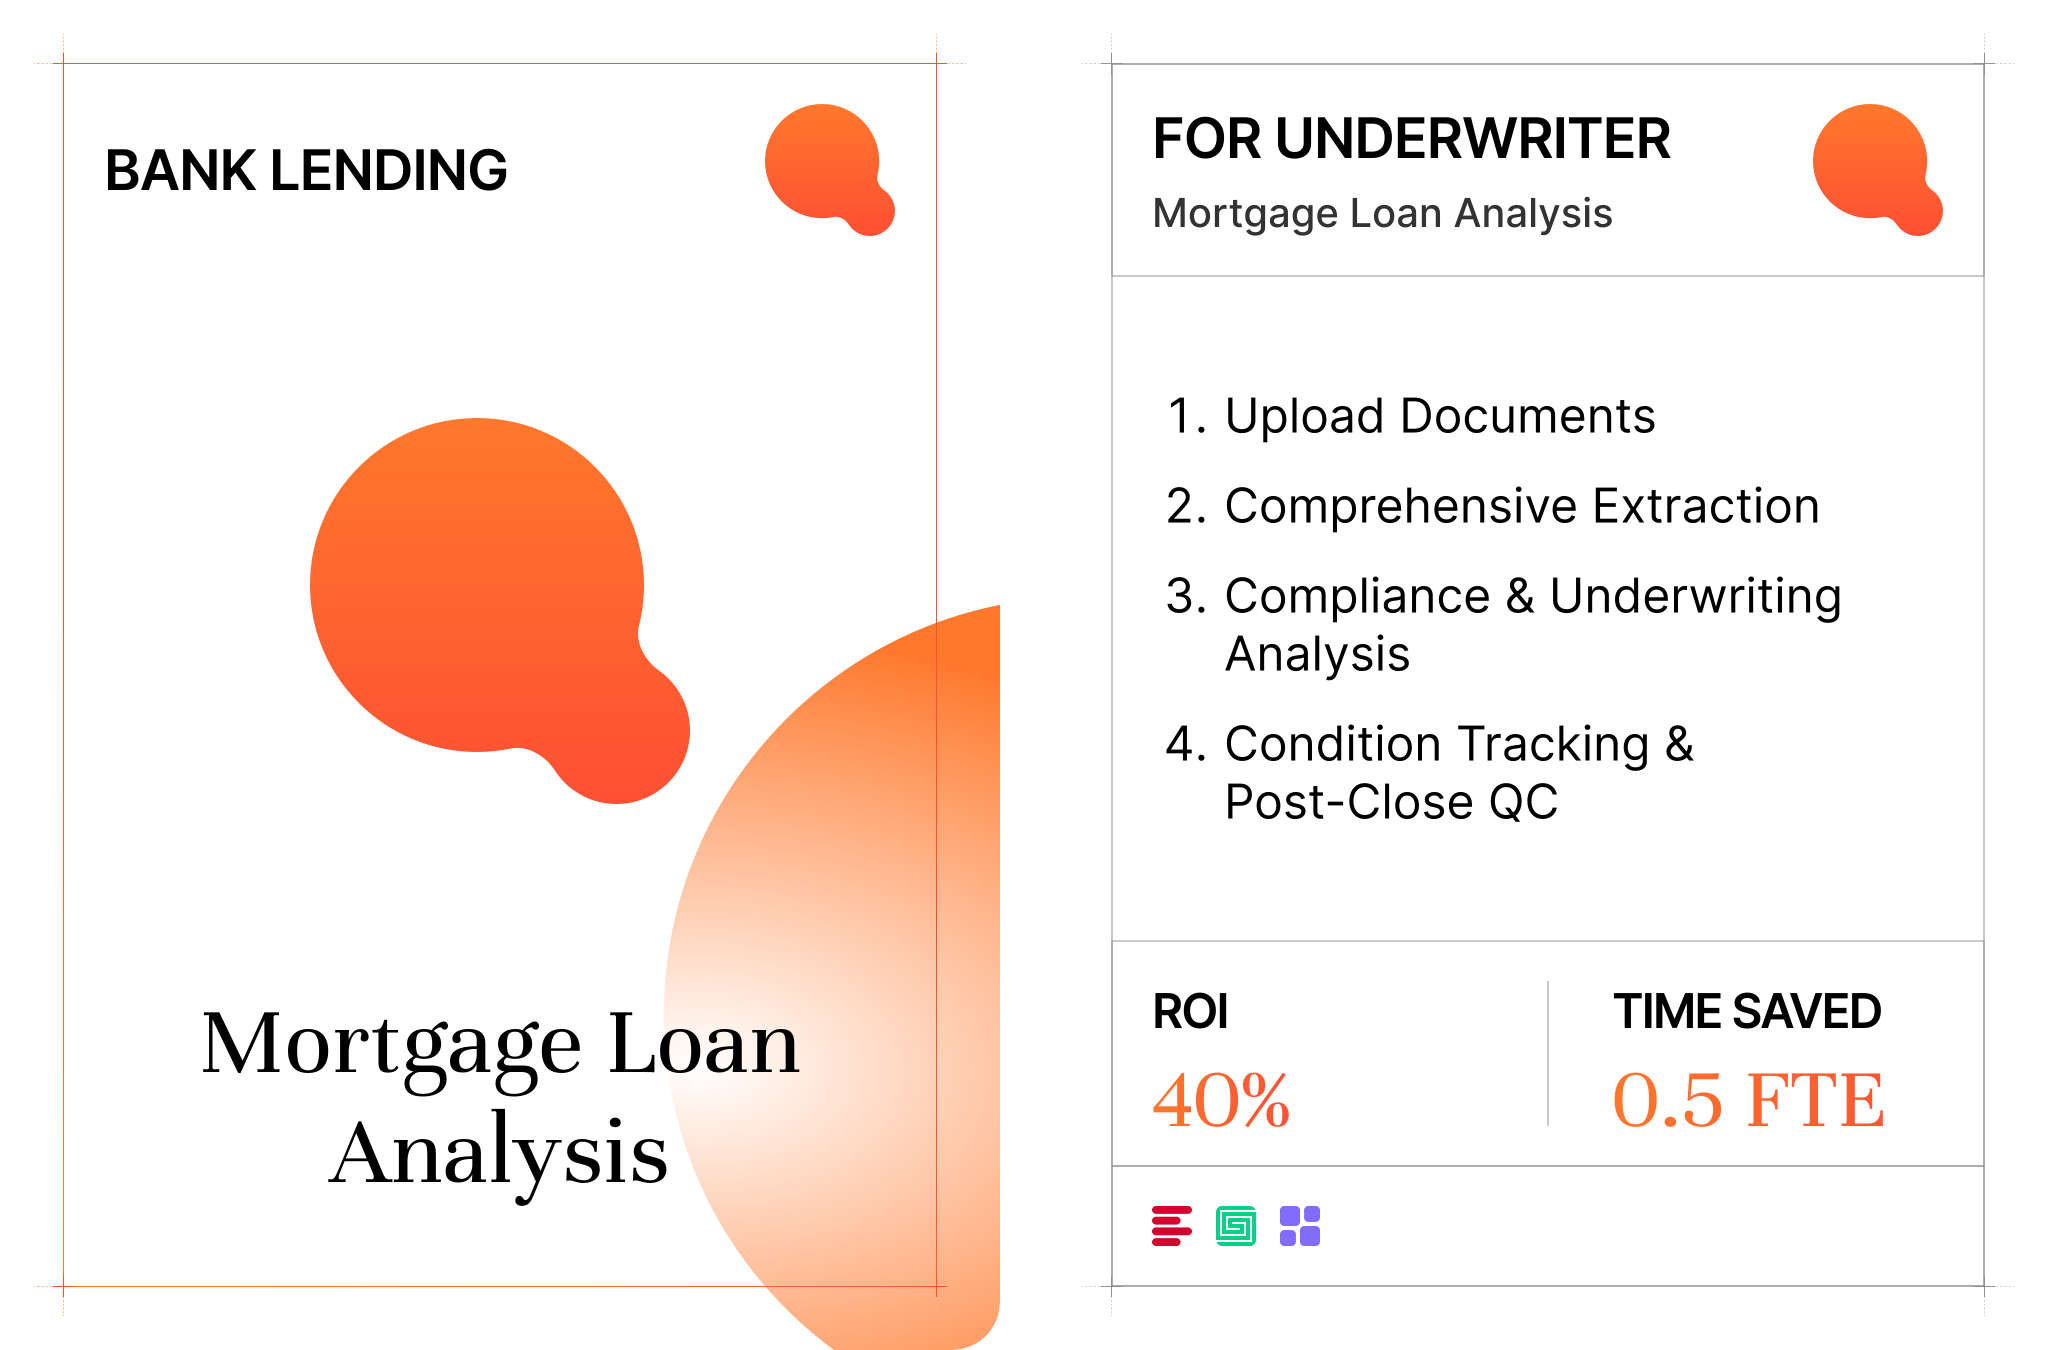

Posh AI is conversational AI for banking. AgentFlow is the operational AI layer underneath it. Posh answers the member on the phone, on the website, and in chat. AgentFlow processes the loan file that conversation creates: the documents, the stipulations, the decision, and the audit trail. Most credit unions can run both without conflict.
If you searched for a Posh AI alternative, start by naming what you actually want to replace. The answer points in two different directions, and getting it wrong costs money and a year of your technology plan.
What is Posh AI? A conversational AI platform for banks and credit unions
125+
Financial institutions on the Posh platform, as of August 2026
300+
Deployments across those institutions
91%
Of 30,000 monthly calls solved by Florida Credit Union's voice assistant
Posh AI is a conversational AI platform for banks and credit unions, founded in 2018 by Karan Kashyap and Matt McEachern out of MIT.
Posh products for customers and employees
Posh splits its platform into tools for customers and employees, all built on REALM, its proprietary reasoning engine.
Voice Assistant
A 24/7 voice agent for phone systems, answering FAQs, routing calls, and automating routine transactions
Digital Assistant
Web chat and mobile banking chat for members
Posh Answers
A website assistant that turns every page into an AI help center, with lead capture
Posh Outreach
Proactive AI agents that reach customers first, launched April 2026
Knowledge Assistant
AI answers for internal teams, drawn from the institution's own policies
Posh CoachQA
Evaluates 100% of conversations for compliance and performance, launched March 2026
What Posh integrates with
Posh integrates with core banking systems and contact-center platforms rather than replacing them. Its published core list covers COCC, Corelation, Fiserv, Jack Henry and Symitar, alongside telephony and online banking platforms including Genesys, NICE, Twilio, Alkami and Q2. Posh joined the Jack Henry Vendor Integration Program in April 2025 and announced a Corelation referral partnership in May 2025.
What Posh does well
Give credit where it is due. A good voice assistant deflects the calls nobody on your human team wanted anyway, and it works around the clock. Florida Credit Union's voice assistant, Flora, "handles over 30,000 calls a month, solving an average of 91% of the requests," per Posh's published client story. Posh separately headlines Ion Bank at a 95% containment rate.
AI phone support that runs 24/7 also reaches members who cannot call during branch hours, and automating repetitive interactions reduces front-line burnout. Posh Outreach extends this by activating member signals to drive proactive engagement across voice, SMS, email, push notifications, and personalized microsites.
What Posh does not cover:
Posh does not extract data from loan documents, automate lending workflows, or generate decision-level compliance audit trails. Its Knowledge Assistant reads your institution's own policies for your staff, which saves real hours, but it does not read a borrower's pay stub. Its lending page describes product coaching, rate and policy answers, and borrower guidance, with no claim to underwriting or loan file processing. Posh's own blog puts it plainly: "We also have more lending-specific options coming soon."
Where each platform operates
Posh is strong at the front office. AgentFlow covers the back office, with AI agents running the loan file from document intake through compliance.
Banking operation
Posh AI
AgentFlow
Customer-facing voice and IVR
✓ Voice agent with natural language
✗ Not customer-facing
Web chat and website answers
✓ Digital Assistant and Posh Answers
✗ Not customer-facing
Proactive outreach across SMS, email and push
✓ Posh Outreach
✗ Not an engagement tool
Employee knowledge for internal teams
✓ Knowledge Assistant
✗ Not employee-facing
Document extraction from loan files
✗ Not built for document extraction
✓ Agents extract, classify, and validate
Lending workflow automation
✗ Not built for lending workflows
✓ Full workflow orchestration
AI-assisted credit decisions
✗ No decisioning
✓ Agents support decisions
Compliance audit trails
✓ Interaction-level trails for conversations
✓ Decision-level trails for lending
Specialized tools win in compliance-heavy banking scenarios. A platform built for conversations produces a record of the conversation. A platform built for lending decisions produces a decision record. An examiner asks for the second one.
Posh AI alternative
Looking for a Posh AI alternative?
Strong alternatives to Posh AI depend entirely on what you are trying to fix, so name the problem before you shortlist vendors.
If you want a different conversational AI or voice assistant
Posh's real competitors here are other front-office companies. The ones credit unions most often compare against Posh:
Eltropy
Messaging, voice and chat for community financial institutions, serving more than 750 institutions across North America.
interface.ai
Voice and chat agents built for banks and credit unions.
Glia
Digital member service and voice across channels, with 700+ banks, credit unions and financial institutions.
Kasisto
The KAI platform and KAI-GPT, positioned for community banks and credit unions.
Top competitors offer strong feature parity, so the difference comes down to integrations, setup effort, channel mix across voice, chat and SMS, conversation quality, AI-to-human hot handoffs, and pricing.
On pricing, one detail worth pulling on.
Posh does not publish pricing. Neither do Eltropy, interface.ai, or Kasisto. Glia publishes a model with no per-seat, per-minute or per-token charges. Ask every vendor whether the invoice is per call, per minute, per seat, or a flat monthly subscription. The answer decides whether success gets more expensive as you scale.
Note on Eltropy specifically.
Its March 2026 agentic platform launch quotes a chief product officer describing agents that "already authenticate members and provide account information," with payments, loan system updates, and collections named as areas the company is rapidly expanding into. Read the roadmap as a roadmap.
If what you need is the back-office work automated
Members get their answers. The loan files, documents, and stips still pile up for your human team.
That is a different category: AgentFlow, the operational AI layer that processes the file the conversation creates. For most credit unions, the smartest move is to keep the front-office platform you have and add back-office automation underneath it.
What happens to the loan file after the conversation ends
Follow one member through, and the handoff point becomes obvious.
01
A member asks about a HELOC or an auto loan by voice or chat. Posh answers, checks rates and policy, and guides them to apply.
02
The application arrives with attachments: pay stubs, tax returns, bank statements, title and insurance documents.
03
Someone opens each file, works out what it is, keys the data into the core or LOS, and checks it against policy.
04
Stipulations are raised, chased, received and rechecked.
05
A decision is made, recorded and evidenced.
06
The core has been updated, and the audit trail has been assembled.
Steps 1 and 2 are conversational AI, and Posh does them well. Steps 3 through 6 are three problems it was never built for.
Problem 1
Document processing
Answering questions about an application is different from extracting data from the documents within it.
Problem 2
Compliance
Lending needs document-level decisioning trails and credit-decision explainability, a different artifact from an interaction log.
Problem 3
Orchestration
Running intake, extraction, underwriting, core updates, and audit-ready completion end-to-end requires a clear trigger and a defined push-and-pull between systems.
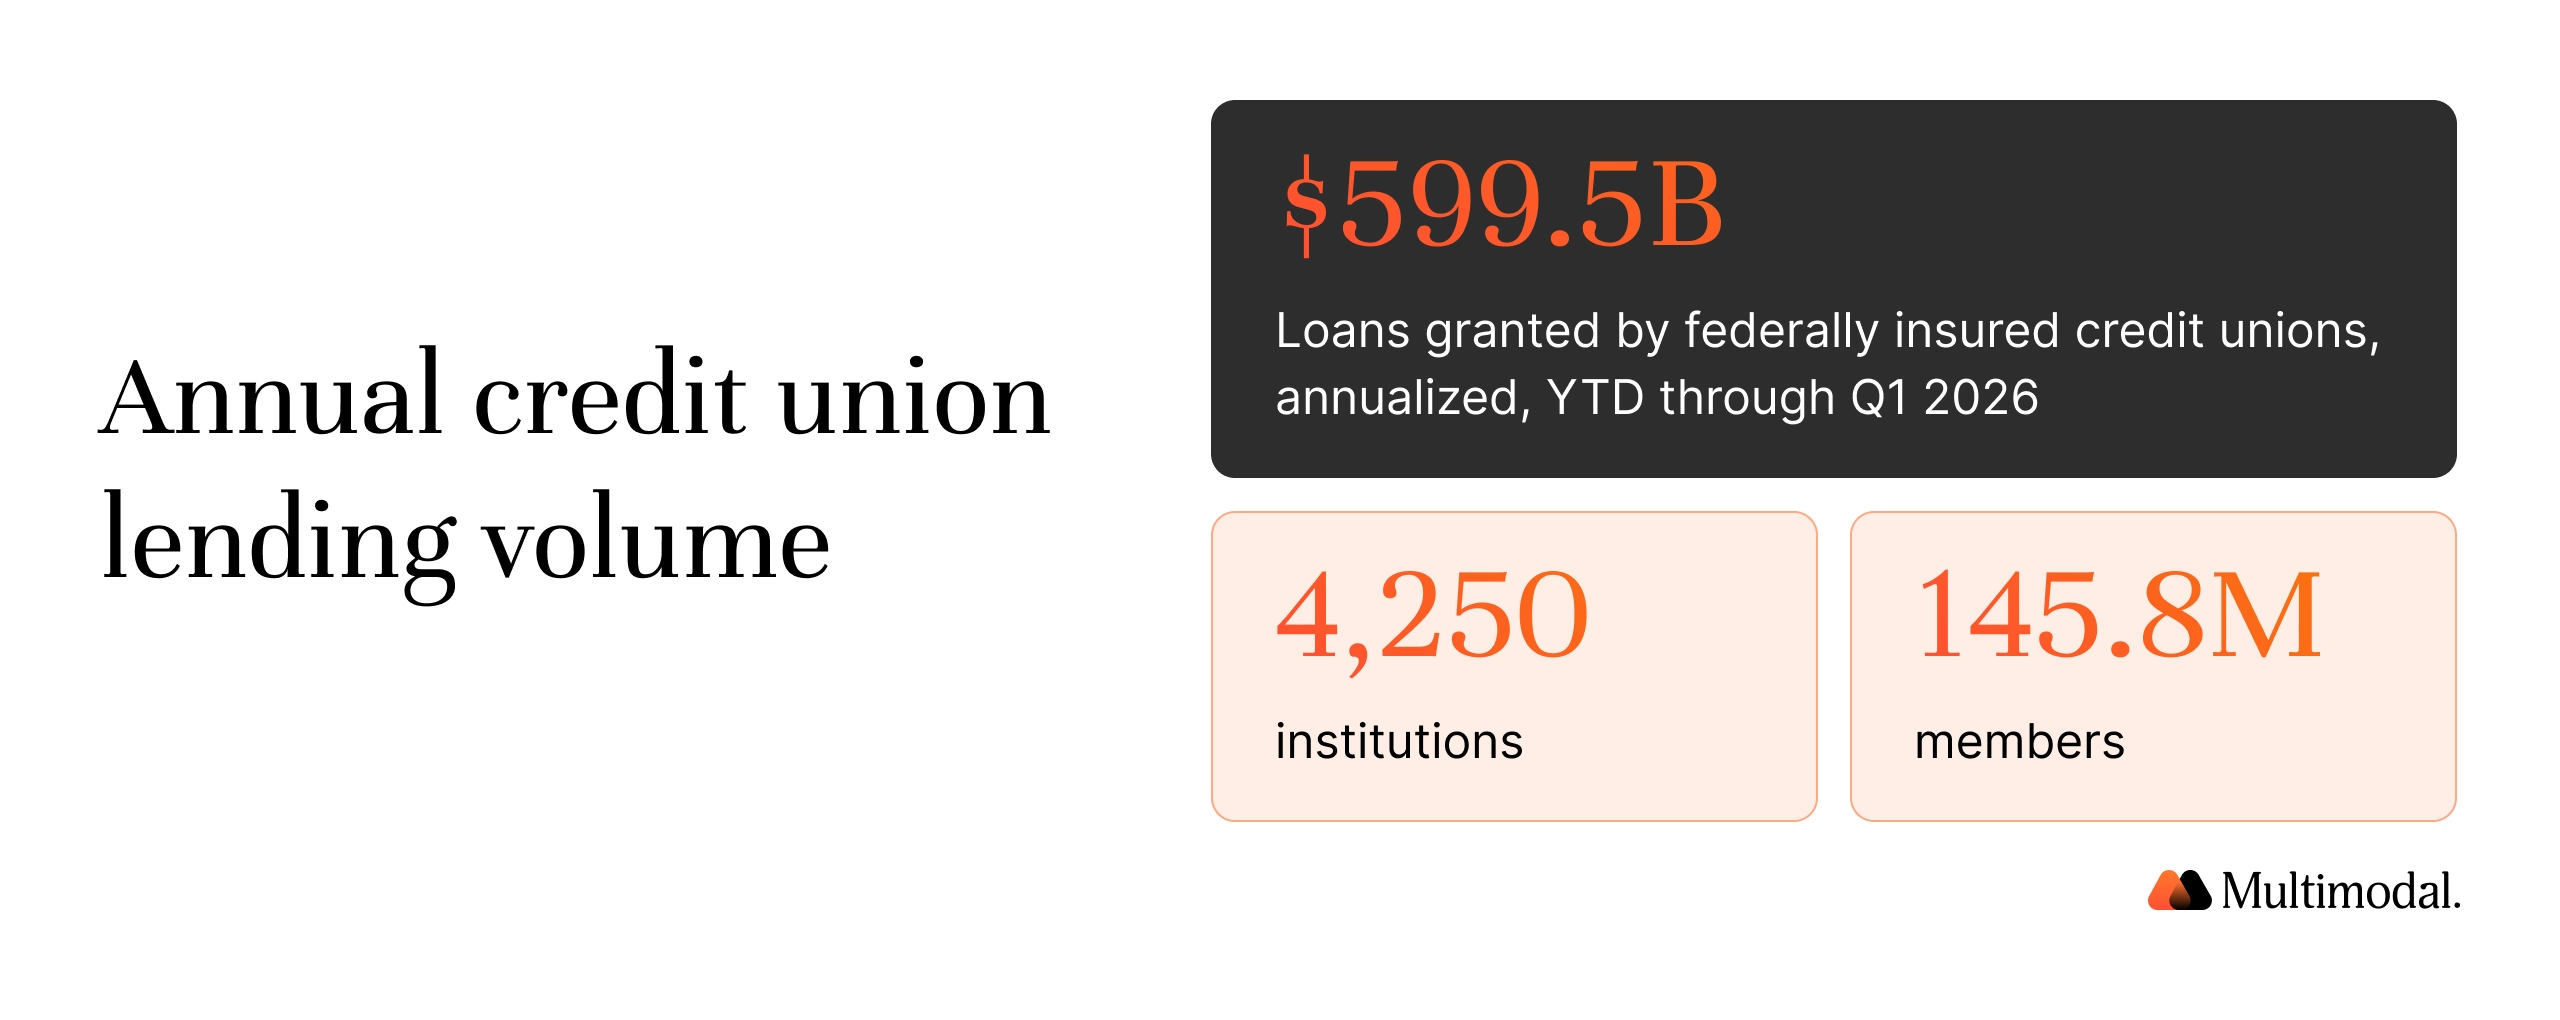
Federally insured credit unions granted $599.5 billion in loans on an annualized basis in the year to date through Q1 2026, across 4,250 institutions serving 145.8 million members, per NCUA's Quarterly Credit Union Data Summary. Every one of those files moves through steps 3 to 6.
Choosing the right platform: a decision framework
Where you invest depends on where the bottleneck sits.
Choose Posh when…
Member service is the priority
- The gap is customer experience: contact centers, web chat, or mobile banking
- Call volumes are high, and your team needs help with routine member questions
- Back-office operations already run fine, and proactive engagement is the opportunity
Choose AgentFlow when…
Lending automation is the priority
- The bottleneck is documents, workflows, and compliance controls for lending
- Internal teams lose hours to manual data entry and document review
- You are being asked to show an examiner how a decision was reached, not just that a call was answered
Deploy both when…
You need complete coverage
- You already run Posh for the call center and are still drowning in loan files
- Posh keeps the conversations, AgentFlow adds the automation underneath
- The two serve complementary roles with no operational conflict
One sizing note worth reading closely. Posh's access programs with the Cooperative Credit Union Association and GoWest are priced for credit unions with less than $300 million in assets. Both name the same two products: Posh Answers and Knowledge Assistant. The Voice Assistant and full Digital Assistant, which drive the marquee results at Citadel, Hudson Valley, and Florida CU, are not included in those discounted packages, so align your expectations with what is in the program.
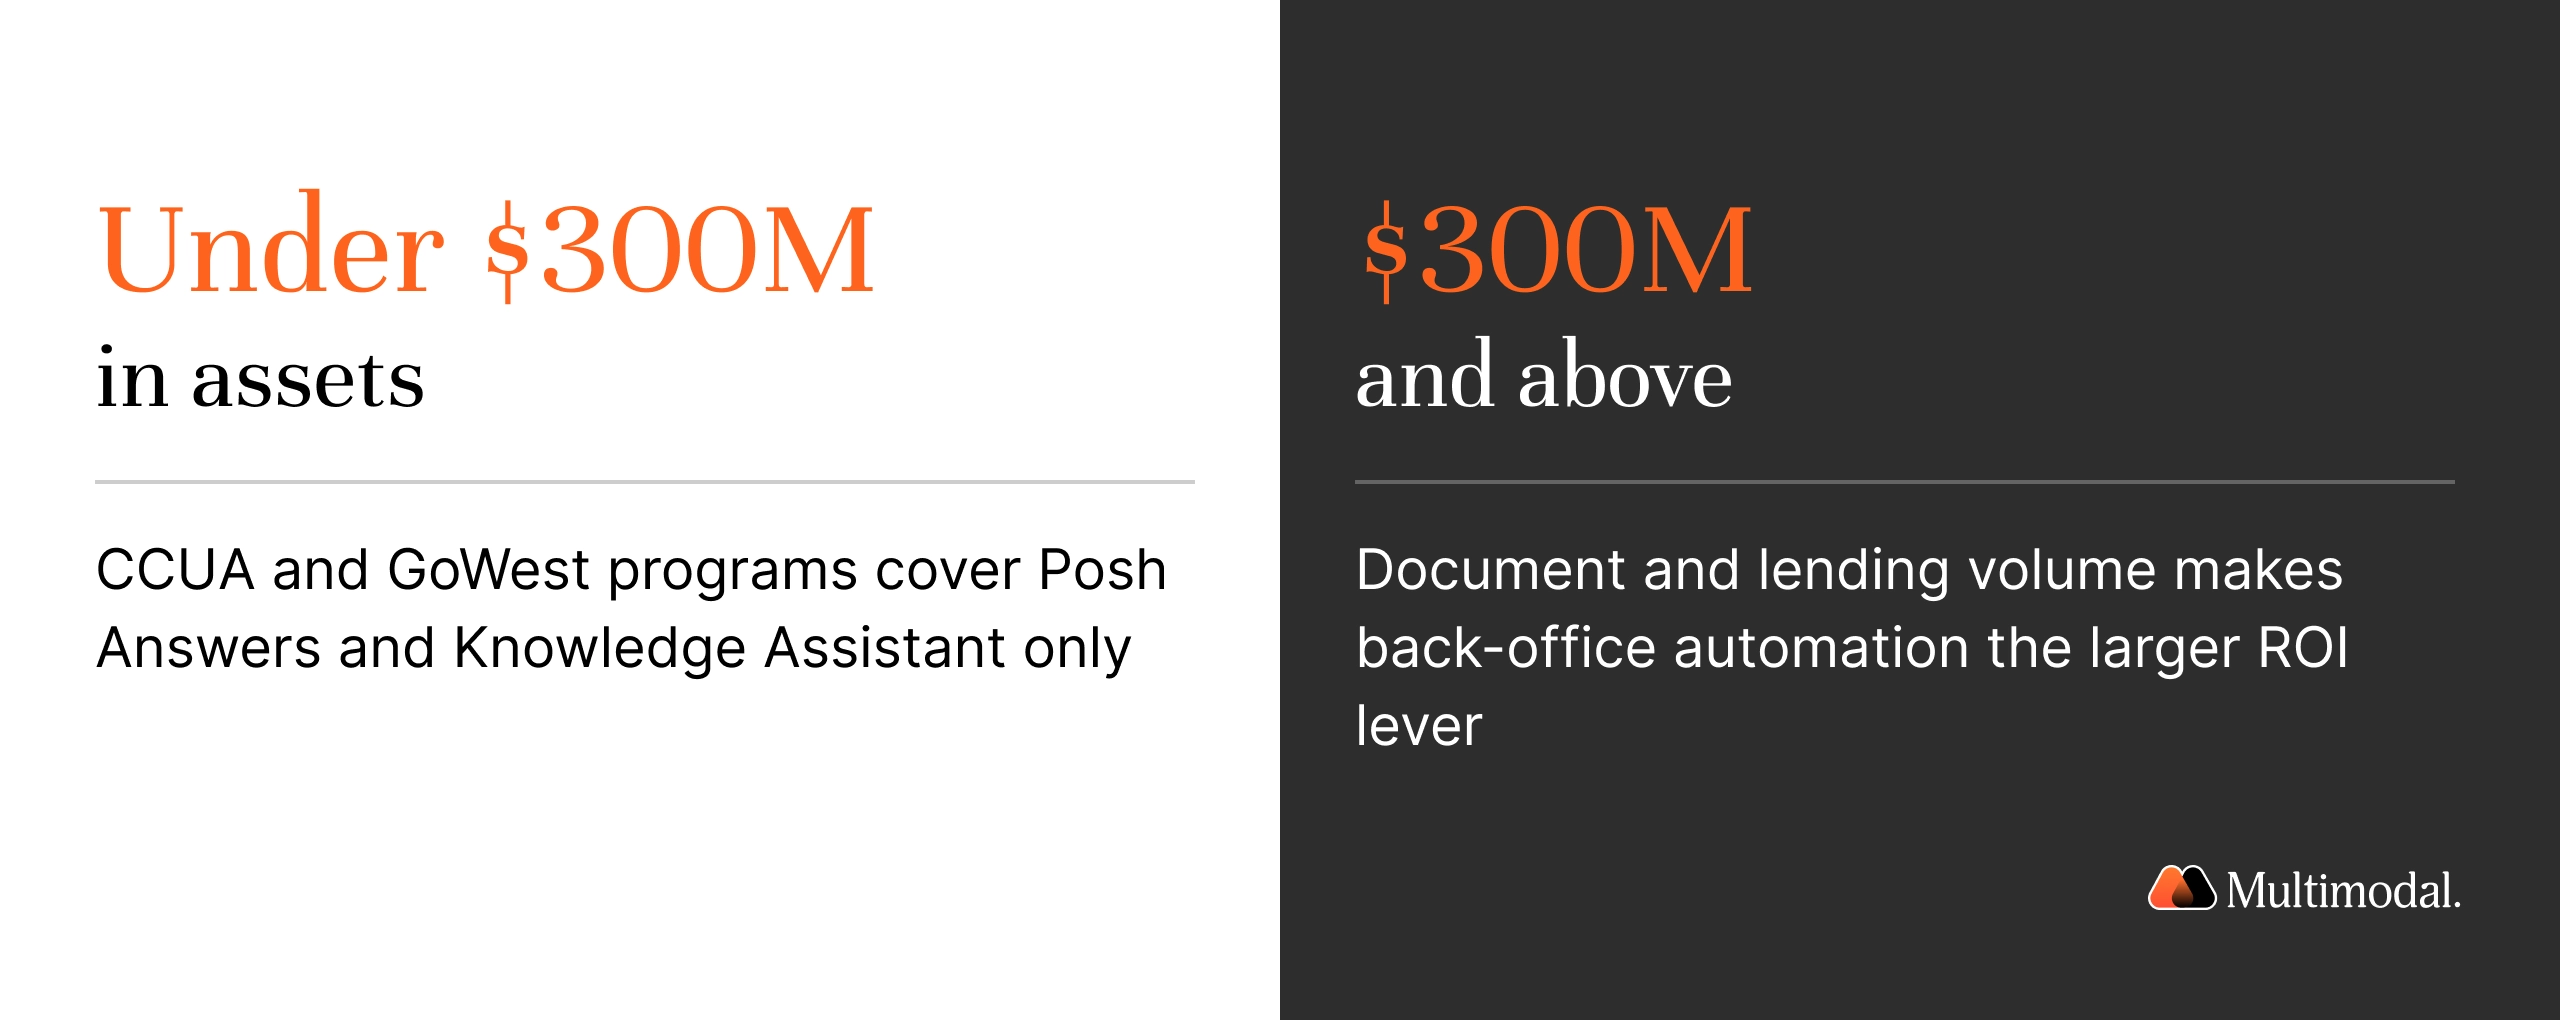
At $300 million and above, document and lending volume usually makes back-office automation the larger ROI lever. That is where AgentFlow concentrates.
Named proof, side by side
Posh publicly names around twenty credit unions. We name two customers. We would rather say that plainly than pretend otherwise.
What Posh publishes
Institution
Assets
Published result
Citadel Credit Union
$6.6B
$663,267 saved in annual third-party costs; overflow spend down 63%, from $1.5M to $389,078
Hudson Valley Credit Union
$8B
201% ROI and $163,000 annual savings on Knowledge Assistant; abandon rate down 46%
Florida Credit Union
$1.9B
Voice assistant handles 30,000+ calls monthly, solving an average of 91% of requests
Sound Credit Union
$3B
82% containment; wait time cut from 1.5 minutes to 19 seconds; roughly $15K+ per month, derived by Posh from 3.5 avoided FTE
Every figure above is vendor-published, drawn from Posh's own client stories.
What AgentFlow publishes
FORUM Credit Union — Fishers, Indiana
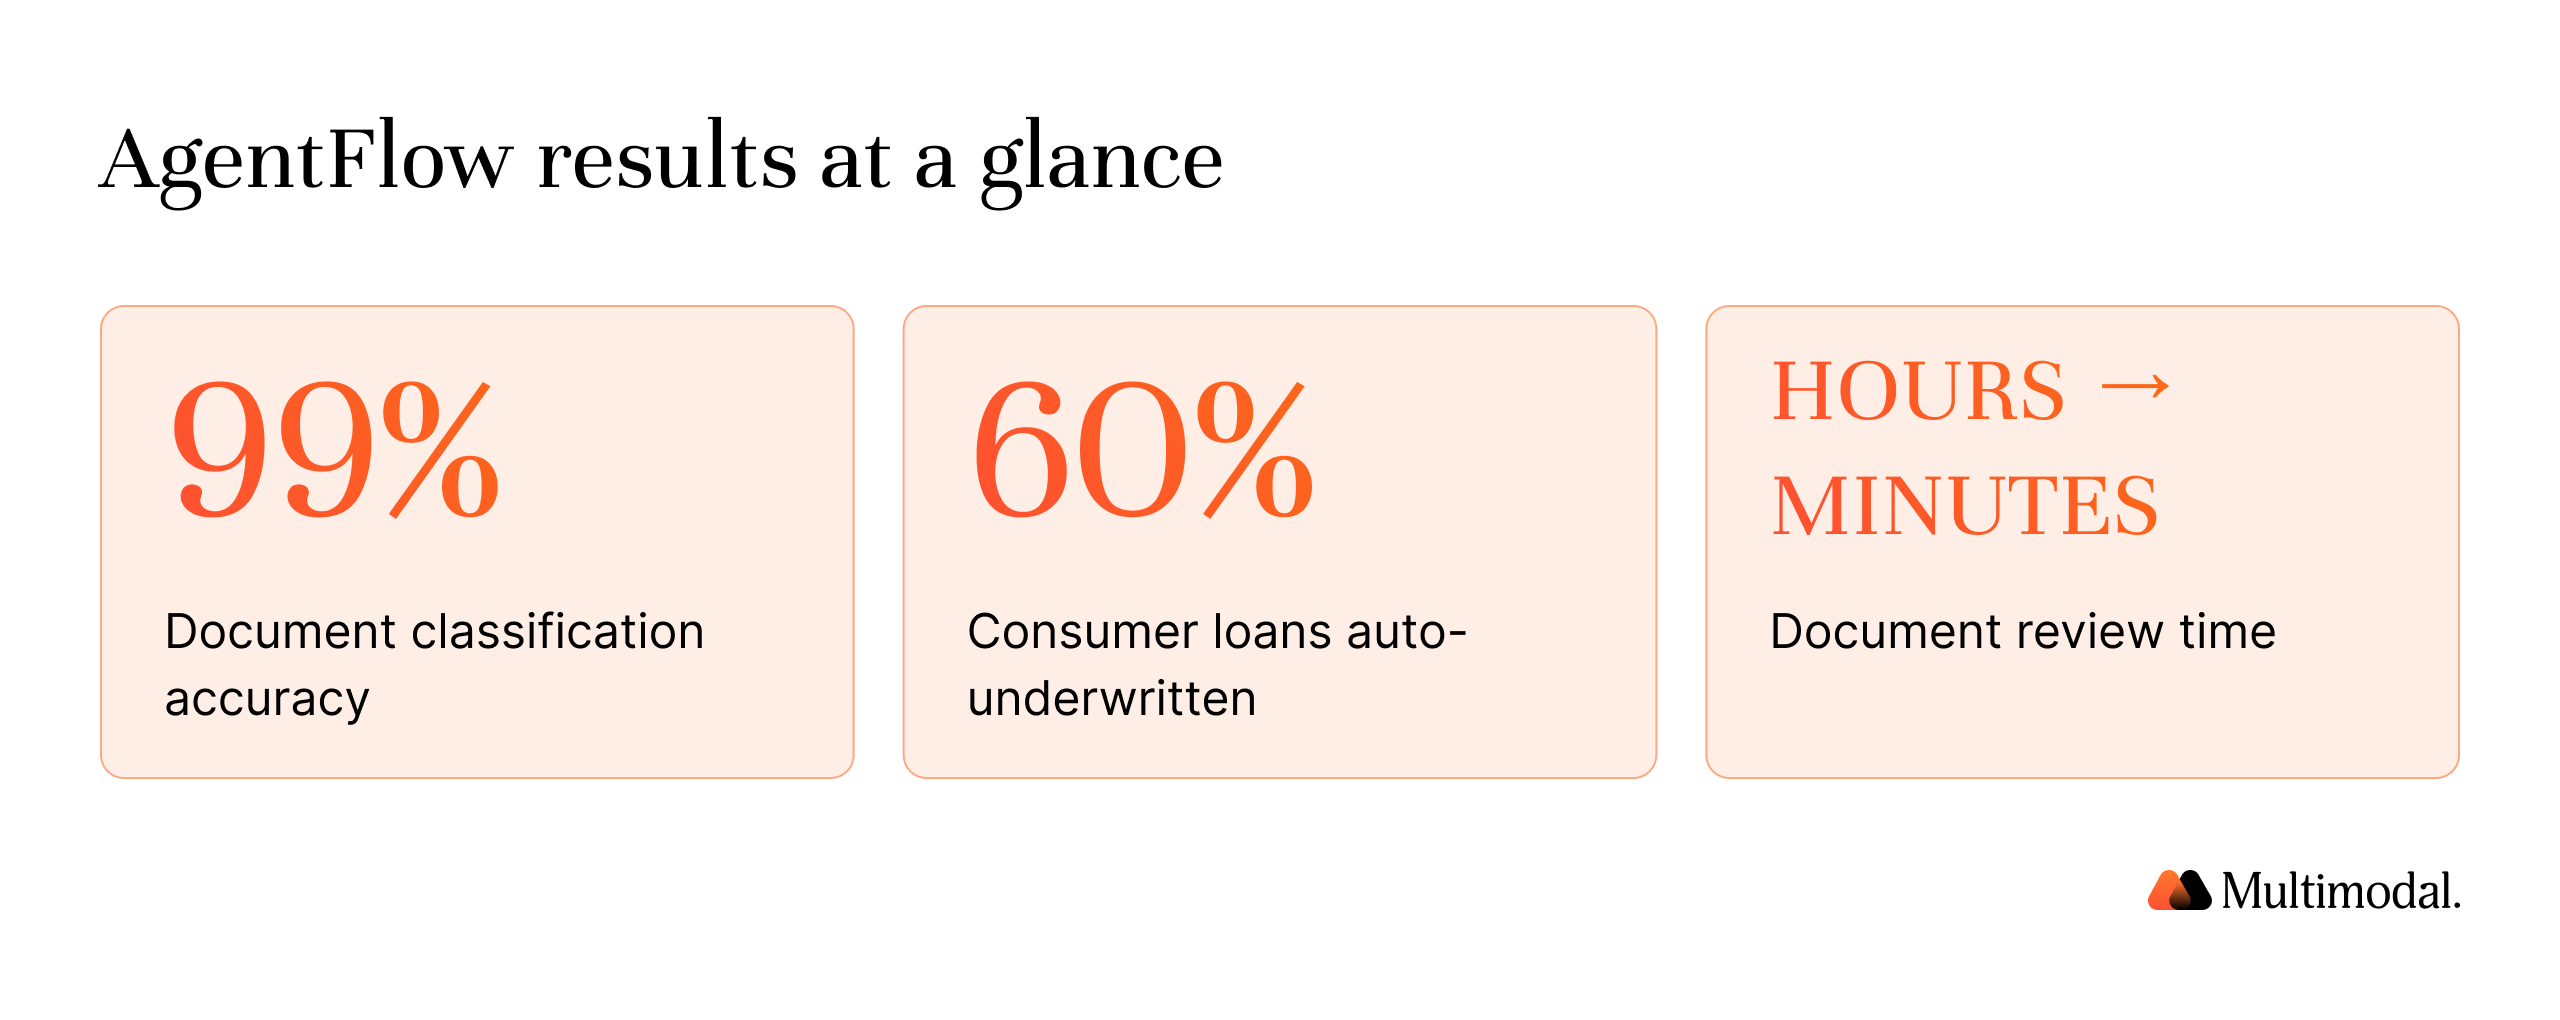
99%
Document classification accuracy
60%
Consumer loans auto-underwritten
Hours → Minutes
Document review time
- 99% document classification and extraction accuracy
- 60% of consumer loans auto-underwritten
- Document review reduced from hours to minutes, with agents handling the entire loan file
"There's a lot of easy decisions, so many easy decisions that we don't need to have a human look at it." — Andy Mattingly, COO, FORUM Credit Union
80%
Cost reduction per processed document
20x
Faster approvals
- Loan processing down from 10 weeks to 5
- Document backlog cut from 1,199 to 4 between May 2024 and January 2025
The part most comparison pages leave out
Neither company has meaningful independent review volume. Posh AI has a single G2 review with a rating of 5.0. Multimodal has a single G2 review with a rating of 5.0. AgentFlow is listed on Capterra with no reviews yet. Posh appeared in Gartner's 2024 Hype Cycle for Generative AI in Banking, which is an inclusion rather than a leadership rating. Do not buy either platform on logo counts. Ask both vendors for reference calls with institutions your size, on your core.
Five questions to ask both vendors
- Which of my systems do you integrate with today, by name, and is that integration live at another credit union on my core?
- Does the invoice scale per call, per minute, per seat, or is it flat monthly pricing?
- Which products are included in my association or core partnership program, and which are priced separately?
- Where does my data live, who are your subprocessors, and do you train models on it?
- If your platform influences a lending decision, what artifact can I hand to an examiner that shows the inputs, the output, and who approved the logic?
Compliance & governance
Security and trust
Third-party AI risk, and what NCUA actually points credit unions at
NCUA published an Artificial Intelligence Compliance Plan in September 2025 under Chief AI Officer Amber Gravius. Read it carefully before citing it: that plan governs NCUA's internal use of AI as a federal agency and imposes no requirements on credit unions. The credit-union-facing guidance appears on NCUA's AI regulatory compliance resource page and is oriented toward third-party vendor due diligence, citing Letters to Credit Unions 07-CU-13 and 01-CU-20 and asking institutions to identify AI-specific risks, monitor them, and implement controls.
NCUA has issued no AI-specific rule, and its July 2025 board briefing states new requirements would need formal rulemaking. The NIST AI Risk Management Framework it references is voluntary and asks organizations to document the intended purpose, model validation, and human oversight of outputs. That is a vendor question that can be answered with supporting documents, so ask for a data processing addendum, a security addendum, an AI governance addendum, and a vendor list.
SOC 2 Type II
PCI DSS
ISO 27001
Complete audit trail
Model-agnostic
Explainable AI
SSO and RBAC
Private deployments
Human-in-the-loop
FAQ
Frequently asked questions
What is Posh AI used for in banking?
Posh AI is a conversational AI platform providing voice automation, web chat, proactive outreach, and knowledge tools for financial institutions. It lists 125+ institutional clients and 300+ deployments as of August 2026, and publicly names around 20 credit unions, including Citadel, Hudson Valley, VyStar, and Florida Credit Union.
Can Posh AI process loan documents?
No. Posh does not extract data from pay stubs, tax returns, or bank statements, automate underwriting, or generate decision-level audit trails. Its Knowledge Assistant reads your own staff policies. Document and decision work stays manual unless you add a platform built for it.
Can Posh AI and AgentFlow run at the same time?
Yes, with no operational conflict. Conversational AI handles member-facing service through voice and chat. AI agents automate back-office workflows like document extraction and compliance reporting. Many credit unions run this pairing, keeping the front-office tool they already have.
What is the best Posh AI alternative for document processing?
It depends on the goal. For a different voice agent, common alternatives include Eltropy, interface.ai, Glia, and Kasisto. If the real problem is the loan files behind the conversation, the alternative is back-office automation like AgentFlow, which most credit unions run alongside Posh rather than instead of it.
Is Posh AI worth it for credit unions?
For member service, yes, particularly at smaller institutions. Posh deflects routine calls and chats so staff focus on harder cases, and its CCUA and GoWest programs make two of its products affordable for credit unions under $300 million in assets. The honest limit: it does not touch back-office lending work.
What does Posh AI cost?
Posh does not publish pricing, and neither do Eltropy, interface.ai, or Kasisto. Glia publishes a model with no per-seat or per-minute charges. Ask any vendor whether pricing is per call, per minute, per seat, or flat monthly.
Does Posh AI integrate with my core?
Posh publicly lists COCC, Corelation, Fiserv, Jack Henry and Symitar among its core integrations, alongside contact-center platforms including Genesys, NICE and Twilio. Confirm your specific core and telephony combination with Posh directly.
How long does AgentFlow take to deploy?
About 90 days to full production, using forward-deployed engineering and prebuilt Playbooks.

See the full lending pipeline beyond conversational AI
AgentFlow automates the back-office work that conversational AI platforms do not cover. It frees your lending teams to focus on exceptions and saves money on manual processing, while agents handle routine documents, processes, and compliance.